Find us at booth #83, join us for a harbor side happy hour, or catch Gorish’s talk.

Sept, 16-18 > Learn more

Tamanna Mishra

August 30, 2026
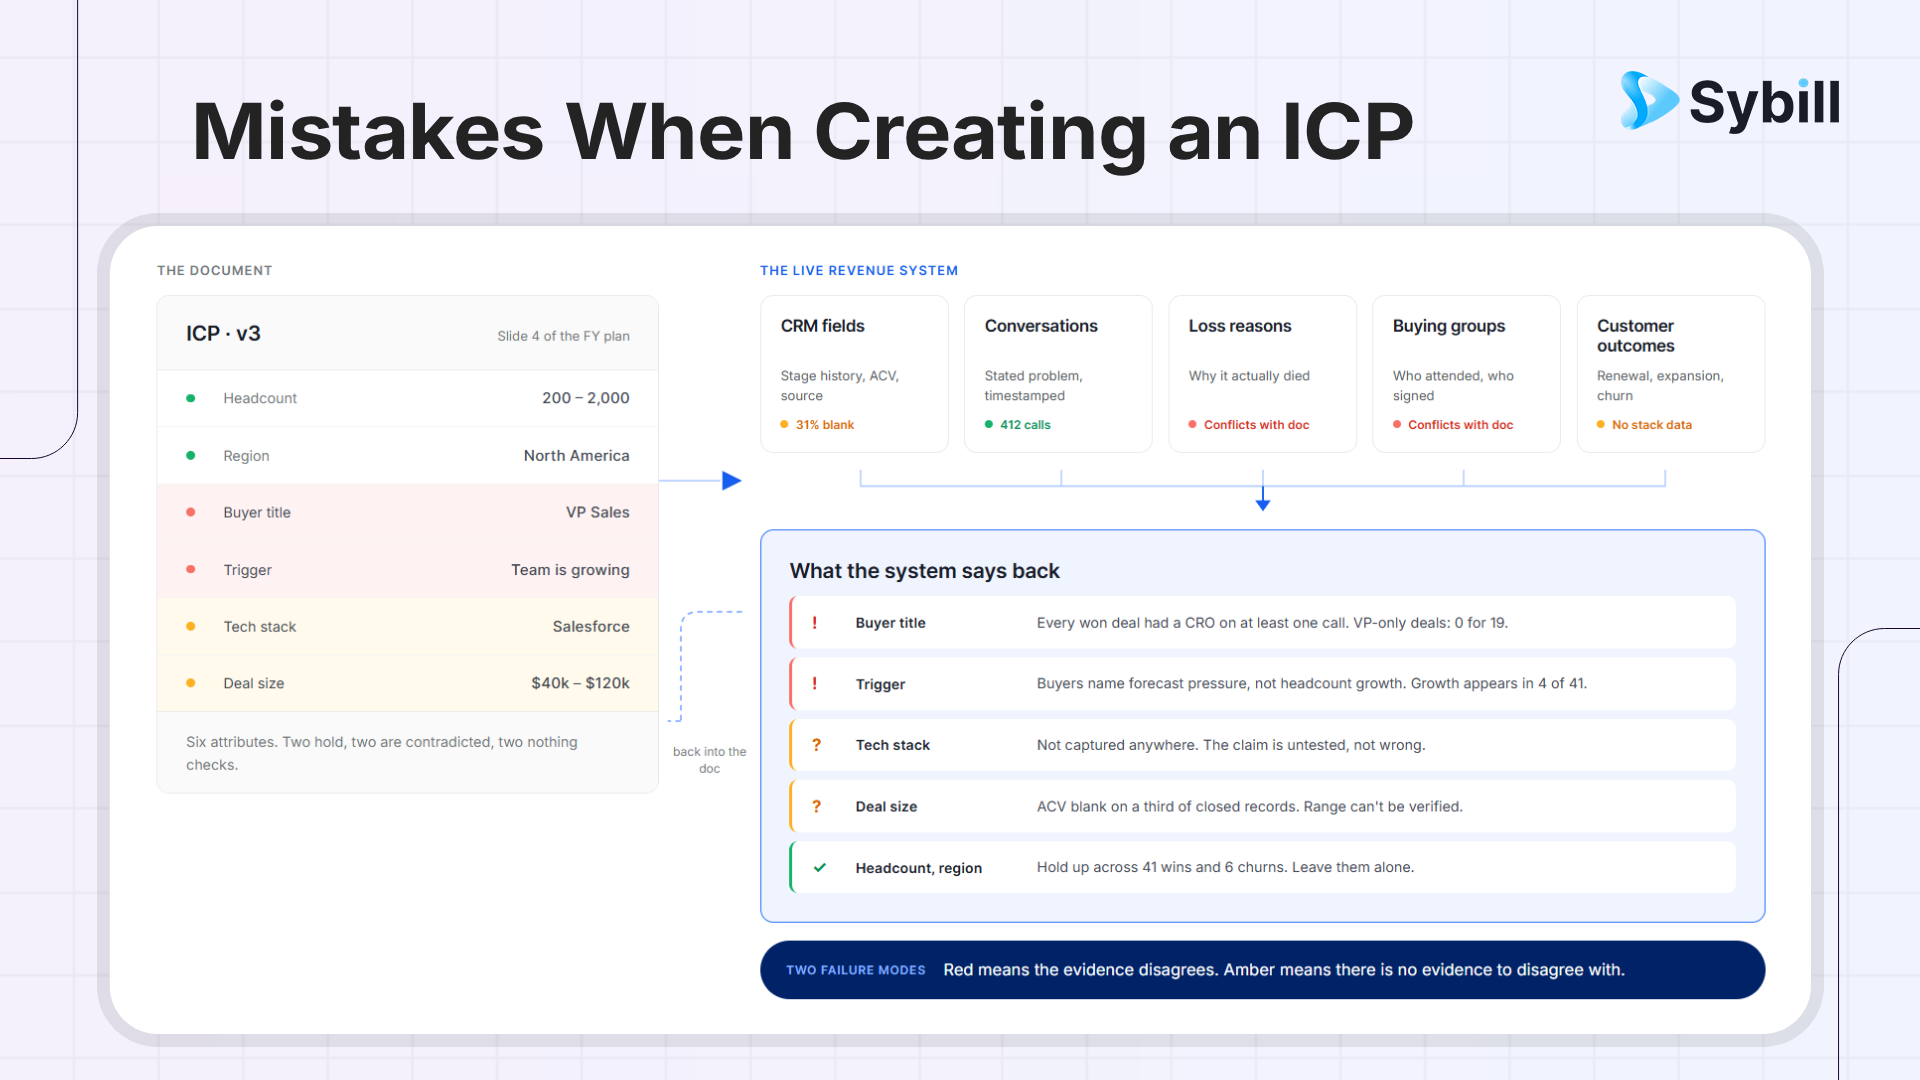
The most common ICP mistakes begin when a company builds its ideal customer profile from assumptions, incomplete CRM records or a handful of memorable deals.
Sybill has analyzed more than 33 million sales calls. The review revealed a more fundamental problem: even a sensible ICP cannot improve if your revenue systems cannot identify who fits it, explain why deals are lost or feed customer outcomes back into the model.
The most common mistakes when creating an ICP are:
A strong ICP is not merely a description of accounts you want. It is a testable hypothesis about which companies are likely to buy, succeed, remain customers and grow.
Many teams have an ICP in a strategy deck but no consistent way to apply it to real opportunities. In Sybill’s research, none of the closed-lost opportunity records had a standardized ICP-fit field.
The fix is to operationalize the ICP inside your CRM. At minimum, record the ICP segment, fit score, positive-fit reason, negative-fit reason, profile version, purchase-readiness score and evidence-backed loss reason. Connect those records to post-sale adoption, retention and expansion wherever possible.
CRM Autofill can preserve qualification and buyer evidence from sales conversations instead of relying on reps to reconstruct it later. RevOps must still define and govern the ICP fields. Automation improves the feedback loop; it does not decide what “ideal” means for your business.
An ideal customer is not simply the logo you would like to win. Nor is it every company sales has managed to close.
Start with customers that received value. Compare retention, expansion, product adoption, time to value, margin, implementation effort and support demand. A prestigious account that required heavy discounting, months of custom work and constant support may be less ideal than a smaller customer that adopted quickly and expanded.
6sense highlights the blind spot in building an ICP from closed-won data alone: it tells you who bought, not necessarily who was best served.
How to fix it: Compare at least three cohorts: successful customers, weak-outcome wins and meaningful losses. Build positive and negative-fit criteria from the differences. For the complete process, see Sybill’s AI ideal customer profile guide.
Some teams worry that a specific ICP will reduce their addressable market. They respond by producing profiles such as “mid-market technology companies” or “B2B companies with growing sales teams.” Those descriptions exclude almost nothing and help reps prioritize almost nobody.
As Salesforce notes:
“The number one mistake people make when drafting an ICP is casting too wide a net for their ideal customers.”
Your total addressable market can remain large. Your ICP exists to identify the accounts that deserve disproportionate attention within it.
How to fix it: Add exclusion criteria. Specify the use cases, technologies, operational maturity, implementation capacity and buying conditions that make an account unsuitable. If your ICP cannot help a rep say no, it is not focused enough.
Industry, revenue, geography and headcount tell you what a company looks like. They do not tell you why it might buy or whether your product fits its operating reality.
An actionable ICP also needs:
Two companies with the same headcount and industry may have entirely different motivations. One may be replacing an expensive incumbent. Another may need cleaner CRM data. A third may want to improve coaching consistency. Treating them as one audience produces generic messaging and weak qualification.
Sybill’s Buyer Intelligence surfaces recurring pains, goals, objections, buying triggers and buyer language across conversations and segments. That helps teams add problem context to the company attributes already available in their CRM and enrichment platforms.
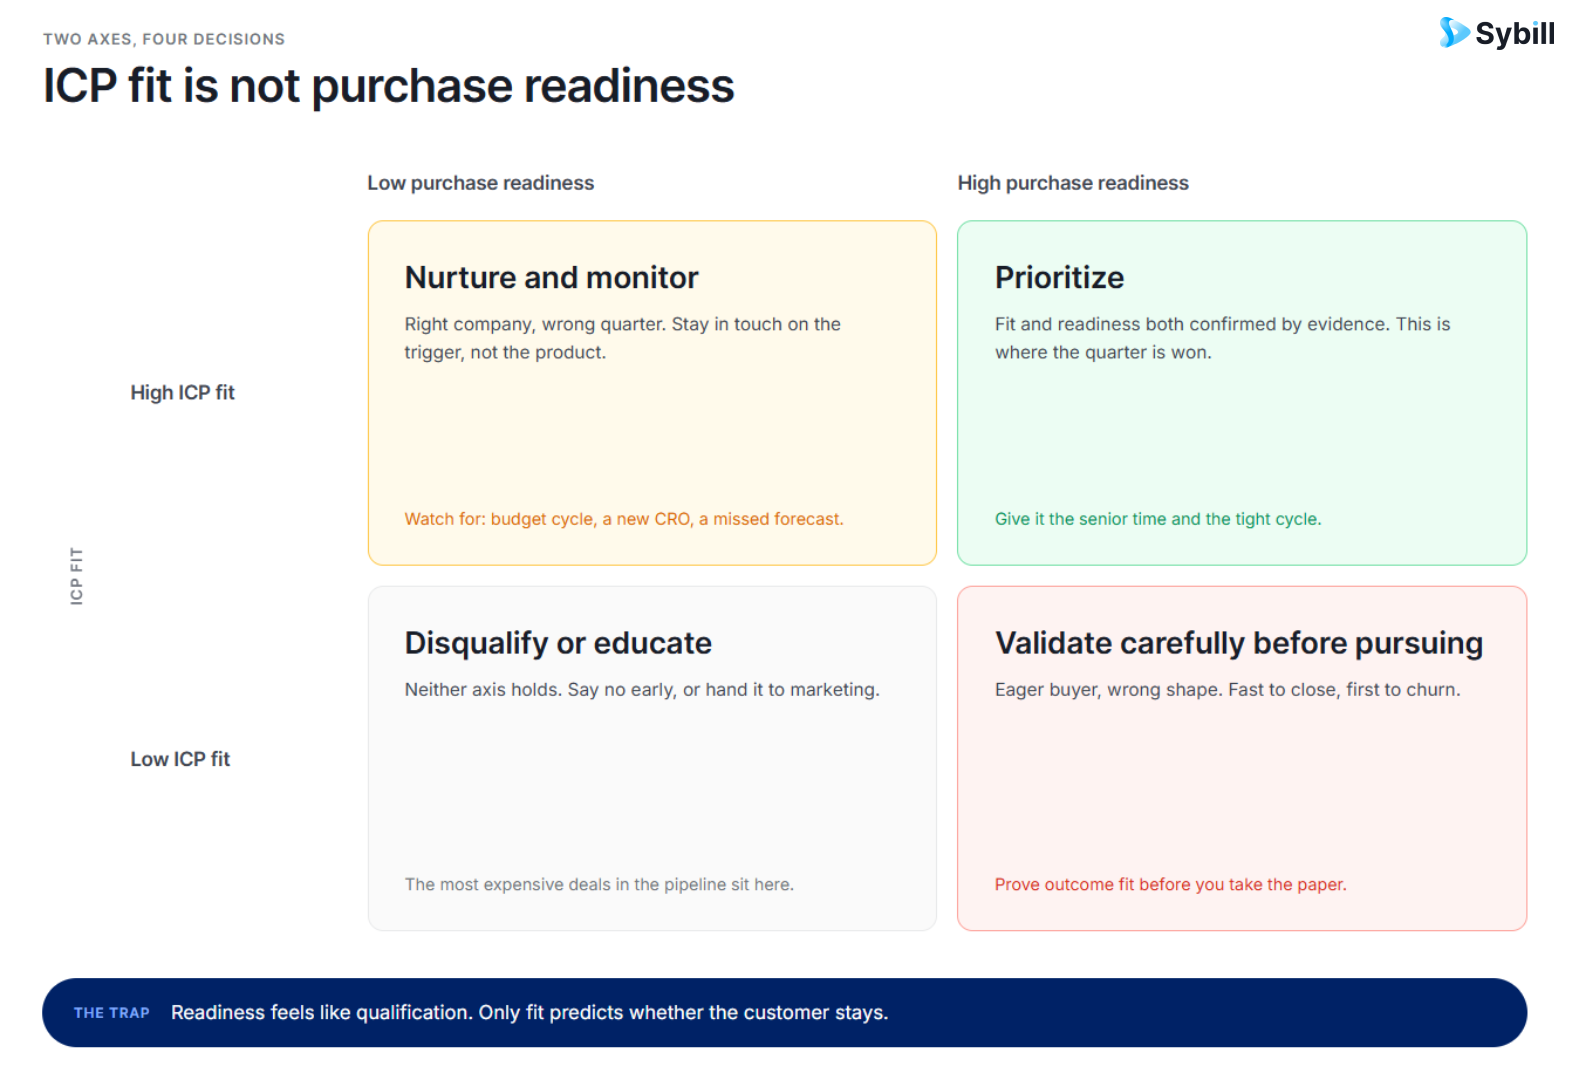
A company can resemble your best customers and still be unable to buy now.
Among the 24 closed-lost opportunities with documented evidence in Sybill’s audit, no decision, timing or deferral was the primary reason recorded in seven. A missing economic buyer appeared as a secondary factor in six, although it was never the sole documented reason.
Hard triggering events were also rare in the temporal sample. None of this proves that timing or stakeholder access caused a loss. It does show why account fit and current buying conditions should not be collapsed into one score.
How to fix it: Maintain separate fields for ICP fit and purchase readiness. Assess urgency, champion strength, economic buyer access, decision process and buyer-committed next steps. Deal Inspection can help teams find missing qualification evidence and inspect whether the buying committee and process are sufficiently developed.
Loss data should improve your ICP. Poorly coded loss data can corrupt it.
Competitor preference and no decision or timing were each recorded as the primary reason in documented losses.
In 50% of competitor losses, the CRM classified the outcome as a competitor win while call outcome summaries indicated a process-timing failure.
If the team accepts “lost to competitor” at face value, it may conclude that the ICP prefers the competitor. A more useful conclusion may be that sales execution missed the decision window.
How to fix it: Record the official loss category, the underlying evidence and whether the factor was controllable. Review the deal history before changing ICP criteria. Sybill’s sales win-loss analysis guide provides a fuller process, while Ask Sybill can retrieve relevant evidence across calls, emails and CRM records.
Aggregate data can make your ICP look cleaner than the market really is.
In the documented sample, competitor preference represented 29% of losses overall.
The same category also contained different problems and buying roles.
How to fix it: Create separate ICP variants when segments have meaningfully different problems, buying triggers, requirements or loss patterns. Then map buyer personas within each account. The ICP describes the company; buyer personas describe the champions, economic buyers, users and blockers involved in the decision.
An ICP becomes stale when the market, product or available alternatives change faster than the profile.
The clearest directional change in Sybill’s temporal sample involved DIY. These were small, non-random samples from one company’s pipeline, so the comparison should not be called a market trend. It still illustrates the problem with a static ICP. A company that used a competitor in 2025 may now combine the competitor’s transcripts, Claude, custom MCPs and internal dashboards. Its firmographics have not changed, but its alternatives, expectations and switching barriers have.
How to fix it: Review ICP performance quarterly and conduct a deeper annual refresh. Trigger an earlier review when new alternatives emerge, product capabilities change, a new segment converts, or retention and expansion patterns shift.
Use this checklist during your next ICP review:
If several answers are no, the solution is not another brainstorming workshop. Repair the evidence loop first. Then use Sybill’s ICP sales playbook to turn the revised profile into qualification criteria, messaging, discovery questions and sales actions.
A strong ICP is not a description leadership approves once. It is a revenue hypothesis that should become more accurate with every win, loss, renewal, expansion and churn event.
Sybill helps revenue teams retrieve buyer evidence, inspect qualification gaps, preserve conversation context and find patterns across deals. Ask Sybill which pains, triggers, objections and stakeholder patterns recur across won and lost opportunities, then use that evidence to test whether your ICP reflects the market you are actually selling into.
Book a Sybill demo to see what your sales conversations can reveal about your ideal customers.
The most common ICP mistakes are relying on assumptions, targeting too broadly, stopping at firmographics, failing to operationalize the profile in CRM, confusing account fit with purchase readiness, trusting weak loss data, blending different segments and failing to update the profile as customers and markets change.
Your ICP is too broad if it cannot exclude unsuitable accounts, rank opportunities or guide meaningfully different messaging. Labels such as “B2B companies” or “mid-market technology businesses” rarely provide enough detail. Add problems, technologies, operating conditions, implementation requirements and negative-fit criteria.
Use CRM opportunity data, firmographics, technographics, sales conversations, buyer interviews, win-loss evidence, product adoption, time to value, retention, expansion, churn and support demand. Compare successful customers with weak-outcome wins and meaningful losses rather than studying closed-won deals alone.
An ICP describes the type of company your business should pursue. A buyer persona describes an individual within that company, such as a champion, user, economic buyer or technical evaluator. The ICP guides account selection. Personas guide stakeholder engagement and messaging.
Review ICP performance quarterly and conduct a deeper refresh at least annually. Update it sooner when your product, pricing, target market, competitive environment, customer outcomes or buying process changes materially.
The most common ICP mistakes are relying on assumptions, targeting too broadly, stopping at firmographics, failing to operationalize the profile in CRM, confusing account fit with purchase readiness, trusting weak loss data, blending different segments and failing to update the profile as customers and markets change.
Your ICP is too broad if it cannot exclude unsuitable accounts, rank opportunities or guide meaningfully different messaging. Labels such as “B2B companies” or “mid-market technology businesses” rarely provide enough detail. Add problems, technologies, operating conditions, implementation requirements and negative-fit criteria.
Use CRM opportunity data, firmographics, technographics, sales conversations, buyer interviews, win-loss evidence, product adoption, time to value, retention, expansion, churn and support demand. Compare successful customers with weak-outcome wins and meaningful losses rather than studying closed-won deals alone.